

How a Hong Kong telecommunications group extended DPO from 30 to 83 days
At a glance
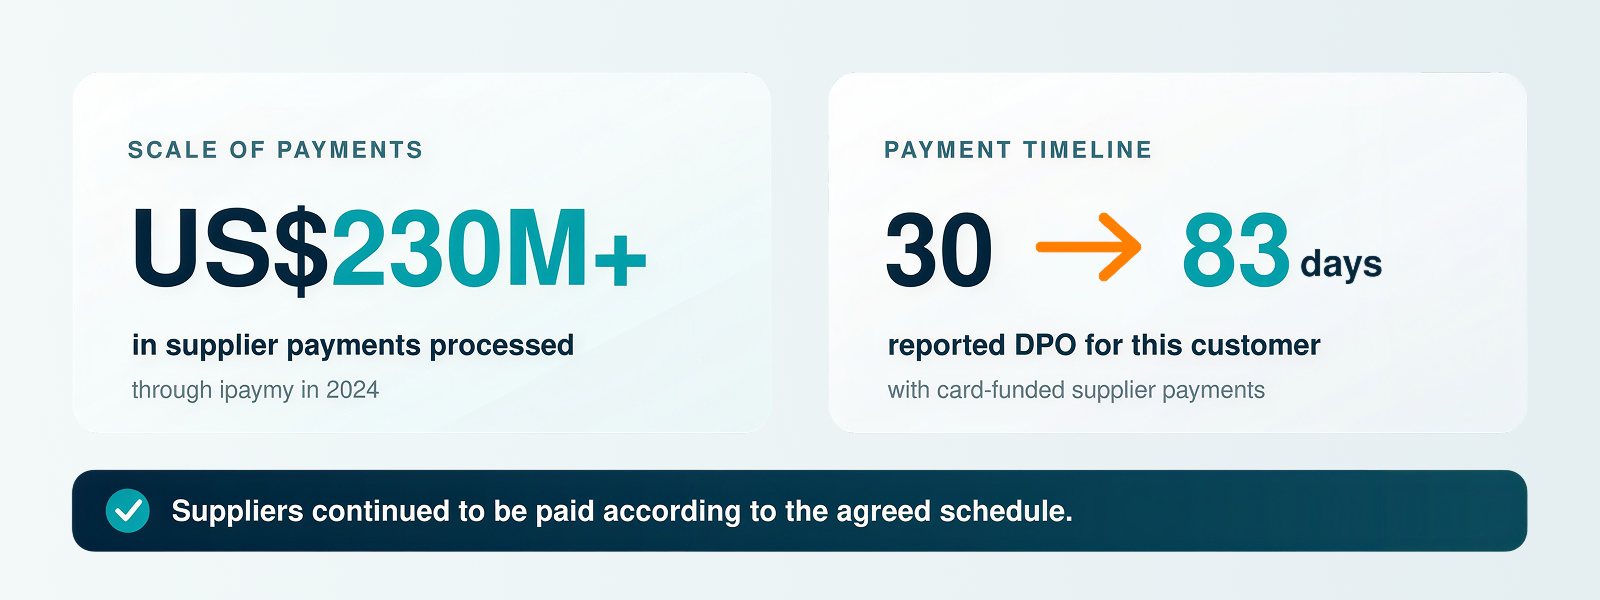
Commercial virtual cards extended the company’s reported DPO from 30 to 83 days without delaying suppliers.
The Hong Kong telecommunications group funded eligible inventory invoices using commercial virtual cards issued by its bank. ipaymy processed the card payments and remitted the approved funds to suppliers by bank transfer. Suppliers remained on their agreed payment schedules and did not need to accept cards, create an ipaymy account or change their invoicing processes.
The challenge
A Hong Kong telecommunications group was managing significant payments for handset and accessory inventory.
These high-value supplier payments placed pressure on the company’s cash-conversion cycle. Extending its payment timeline could create greater working-capital flexibility, but delaying payments to suppliers risked disrupting important commercial relationships.
The company needed an approach that could:
- Extend the effective payment timeline
- Keep suppliers paid according to their existing terms
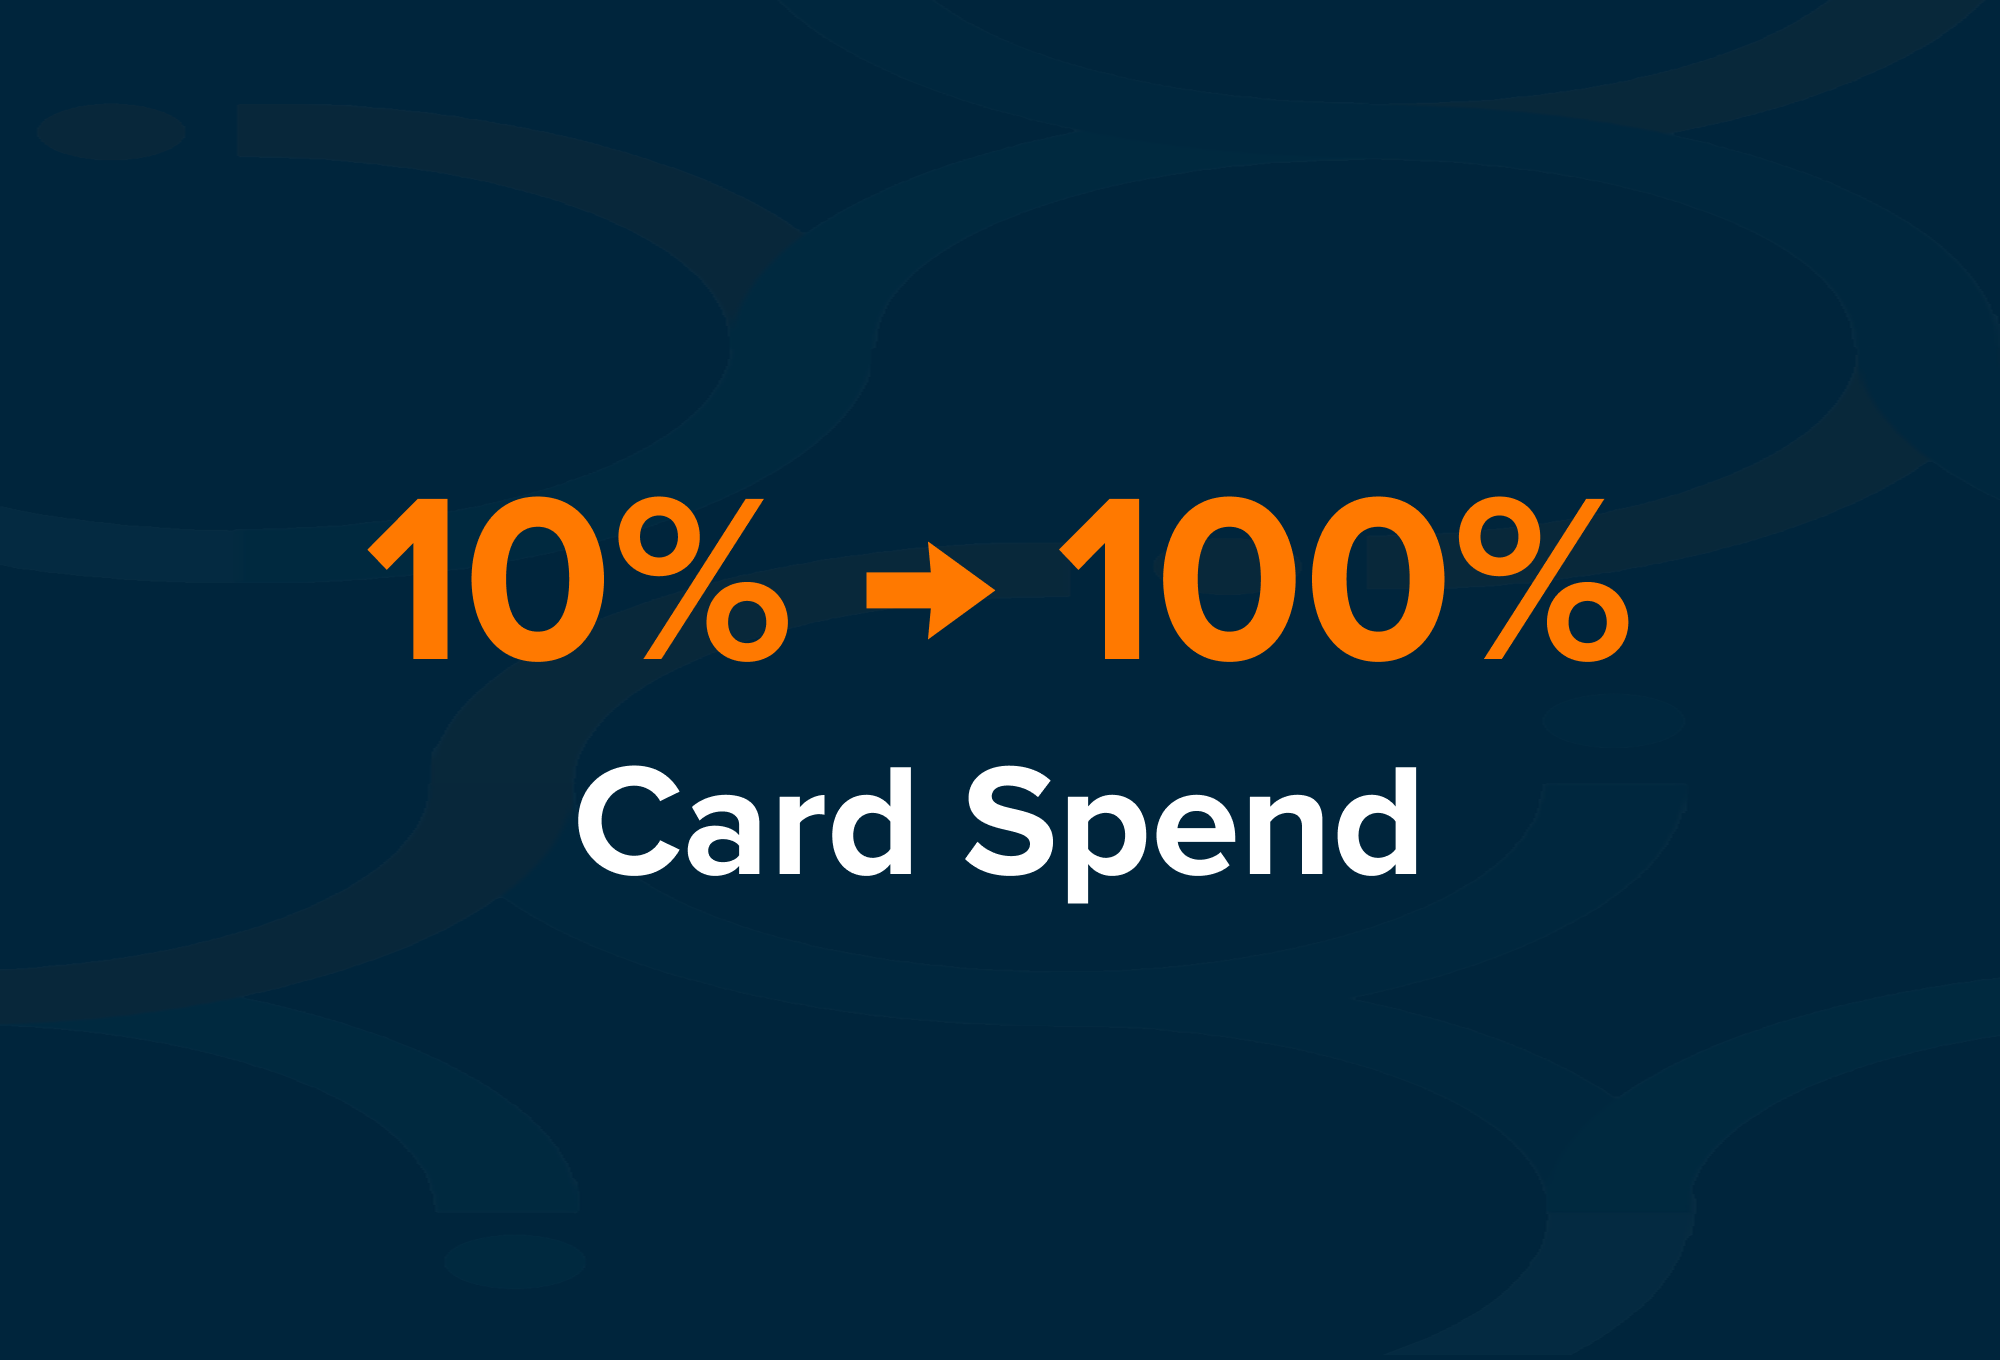
- Make greater use of its commercial-card capacity
- Work without requiring major technology integration
- Minimise additional processing and reconciliation work for the finance team
The challenge was not simply how to pay later. It was how to preserve cash for longer without passing that pressure to suppliers.
The solution
Working with its issuing bank in Hong Kong, the company was issued Mastercard virtual commercial cards and identified suitable supplier invoices for card funding.
ipaymy provided the card-to-account payment layer connecting the company’s commercial cards to its suppliers’ bank accounts.
Instead of paying selected invoices directly from its cash account, the company funded the payments using its designated virtual cards. ipaymy processed the card transactions and transferred the approved funds directly into each supplier’s nominated bank account.
The suppliers continued receiving payments through the same familiar channel. They did not need to accept cards, open an ipaymy account or change how they invoiced the company.
Once the required credit lines and commercial cards had been approved, the solution was implemented in less than two weeks without technology integration.
How the payment flow worked
The company submitted its payment file
ipaymy processed the commercial cards
Payments were authorised and settled
Suppliers received bank transfers
The outcome
The arrangement created measurable working-capital flexibility without changing the suppliers’ existing settlement experience.
Beyond these headline results, the company achieved three broader operational benefits.
Greater working-capital flexibility
- Funding selected supplier invoices through commercial cards created more time between supplier settlement and the company’s final cash outflow.
- This gave the business greater flexibility to manage liquidity around inventory purchases and periods of increased demand.
No disruption for suppliers
- Suppliers did not need to become card-accepting merchants or change their accounts-receivable processes.
- They continued receiving funds directly into their bank accounts, helping the company preserve its existing supplier relationships.
Minimal additional work for finance
- ipaymy handled payment processing, settlement and reporting.
- This gave the company a consistent way to route eligible supplier payments through its commercial-card programme without introducing a major systems project or requiring each supplier to be onboarded for card acceptance.
Why the model worked
The company did not try to change the payment method used by every supplier.
Instead, it separated how the business funded each payment from how the supplier received it:
- The company funded eligible invoices using commercial virtual cards
- ipaymy managed the card-to-account payment flow
- Suppliers continued receiving bank transfers
- The company settled its card obligations according to the applicable issuer terms
This allowed the commercial-card programme to reach suppliers that did not accept cards directly.
The result: more flexibility without supplier strain
By combining its existing commercial-card programme with ipaymy’s card-to-account payment capabilities, the telecommunications group created a more flexible approach to large supplier payments.
More than US$230 million in supplier payments were processed through the solution in 2024. At the same time, the company extended its DPO from 30 to 83 days while keeping supplier settlement processes unchanged.
The result was a payment model that supported working-capital objectives at scale without requiring suppliers to wait longer, accept cards or overhaul their existing processes.
Results basis
Payment volume is based on ipaymy transaction records for 2024. DPO figures were reported by the customer.
Customer confidentiality note
Customer details have been generalised to respect confidentiality. Results are specific to this customer and may vary depending on payment volume, commercial-card terms, market, accounting treatment and operating model.
Ready to transform your payment operations?

Follow us


